

Who You Hire Changes Your Settlement
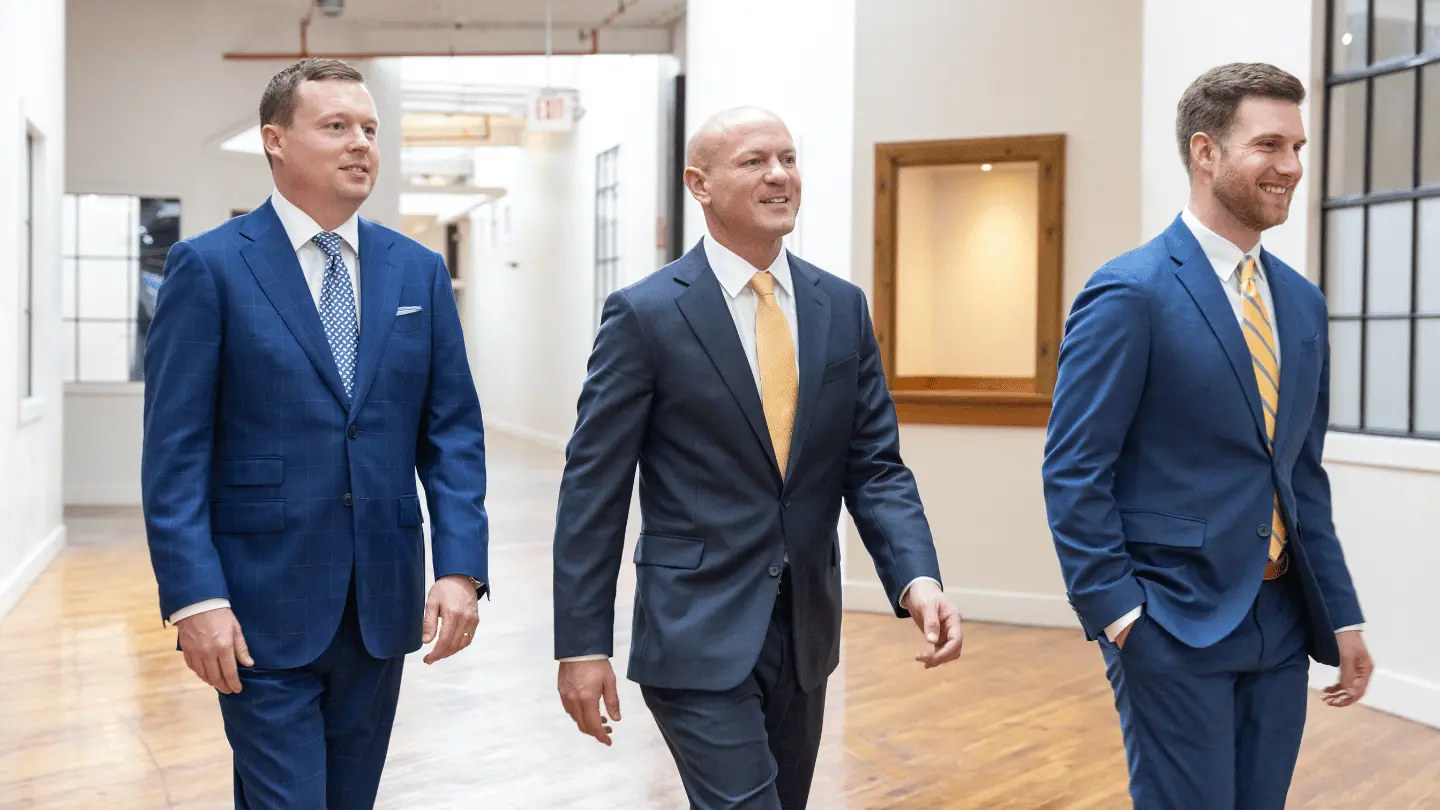
Insurance adjusters used to rely mainly on their own judgment and medical reports to value a claim. That’s changed. Today, major carriers run claims through sophisticated software that applies hundreds of variables to value the claim. The inputs include your medical treatment, injury type, age, and lost wages. They also include data about your attorney.
How Insurance Companies Evaluate Claims
Systems like Colossus, used by carriers representing billions in annual premiums, analyze outcomes across thousands of similar cases. They compare results based on attorney profiles: who settles early, who files suit, who takes cases to verdict, and what those verdicts typically look like. A Consumer Reports investigation into Colossus found that the software was actively calibrated to reduce payouts, and attorney aggressiveness was factored into the model.
What the Software Actually Tracks
When an adjuster or their software looks at your attorney, they’re looking at several factors:
Sam Aguiar founded this firm because regular people were getting outworked by insurance companies with billions in resources.
- Trial rate comes first. Adjusters know which attorneys try cases and which ones settle every file before suit.
- Verdict history follows. What juries award when a firm takes a case to trial shapes the model, and a strong case results page is part of the risk calculation.
- Settlement patterns show whether an attorney pushes back or accepts the first number offered.
- Litigation activity counts. Filing motions, retaining independent professionals, and building serious evidentiary records all register.
- Reputation in the jurisdiction is the last piece. Defense firms and adjusters in Louisville and Lexington know the local bar, and reputation has real dollar value.
What This Means For Your Case
Here’s what this means in real terms: two people with nearly identical injuries, from nearly identical crashes, represented by different attorneys can receive dramatically different settlement offers. The difference is the insurer’s risk calculation.
An attorney with a documented track record of going to trial, securing seven-figure verdicts, and aggressively litigating claims presents more financial risk to an insurer. That risk gets priced into the offer. An attorney who settles quickly and cheaply, or who hasn’t tried a case in years, represents almost no trial risk, and the offer reflects that, too.
How Insurers Score Your Attorney
Major carriers use predictive analytics platforms to score claims and attorney risk simultaneously. The system values your injury and your attorney’s likelihood of making them pay. A trial-ready attorney with documented wins shifts the insurer’s risk score upward. A passive attorney who settles fast shifts it down. That shift is directly reflected in what they offer you.
Traditional Case Factors Still Matter
Insurance adjusters still consider the traditional factors that have always driven personal injury values:
- Severity and type of injury (fractures, surgery, permanent impairment)
- Total medical bills, past and future
- Lost wages and reduced earning capacity
- Pain, suffering, and quality of life impact
- How clearly the other driver was at fault
- Policy limits available
But these factors now interact with the attorney profile. Two claims with similar medical bills can draw sharply different offers based entirely on who is representing the claimant and what the data says about that attorney’s behavior.
The insurance company’s tactics are built around identifying the path of least resistance. Your attorney’s track record either creates resistance or removes it.
What “Trial Ready” Actually Looks Like
Being trial ready means building every case from day one as if it’s going to a jury. That requires:
Every bill, every diagnosis, every future cost projected and documented. No leaving money on the table because a future cost wasn’t identified early.
Economic professionals, treating physicians, and liability professionals engaged and on record. This signals to the adjuster that the case is ready for trial.
Preserved accident footage, witness statements on the record, and physical evidence properly chain-of-custodied. Insurance adjusters know when a case is built for trial versus built for settlement.
With our exclusive Bigger Share Guarantee®, you always get more. $0 Out-Of-Pocket Forever. Get back to living your best life while we do the rest.
What Sam Aguiar Injury Lawyers Brings to the Table
Sam Aguiar is one of only two personal injury attorneys in Kentucky, and one of 16 nationwide, recognized by Forbes as a 2025 Best-In-State Top Lawyer. The firm has secured 40+ Seven-Figure Results Since 2020. Insurance companies in Kentucky and across the country have seen what happens when Sam Aguiar takes a case to verdict.
Every client receives a dedicated team of three: a top-rated attorney, a highly experienced case manager, and a dedicated legal assistant. Cases are built to win. Your fee never increases, even if the case goes to litigation or trial, so quick and cheap settlements work against us too.
If you’re deciding who to hire after an injury, look at the results. Look at the reviews. And know that the other side has already looked at all of it. It’s already factoring into what they plan to offer you.
Ready to Take Action on Your Injury Claim?
After a serious injury, medical bills pile up while the insurance company looks for ways to pay you less. Most law firms take their cut first and leave you with whatever is left. Sam Aguiar Injury Lawyers does things differently. With our exclusive Bigger Share Guarantee®, you always get more. Every client gets a dedicated three-person team: an attorney, a case manager, and a legal assistant. We never raise our fee rate if we have to go to court, and you pay $0 Out-Of-Pocket Forever.
Frequently Asked Questions
1Do insurance companies really track attorney performance?+
2How does hiring a trial-ready attorney affect my settlement?+
3What is the Bigger Share Guarantee®?+
4Does the attorney I hire early on really matter that much?+
5How can I check an attorney’s track record before hiring them?+
6Can I ask the insurance adjuster what software they used to value my claim?+
7My lawyer never goes to trial. Does that actually hurt my case?+
8How does the Colossus software affect what I say to my doctor?+
Latest Articles
Kentucky Minimum Car Insurance Requirements
Kentucky Minimum Car Insurance Requirements Kentucky’s 25/50/25 minimums and $10,000 PIP, explained..
Biggest Mistakes To Avoid After A Car Accident
Biggest Mistakes To Avoid After A Car Accident In Kentucky The insurance company starts protecting its.

Insurance Rates After An Accident
Insurance Rates After An Accident If the accident was not the claimant's fault, rate hikes could be.