

Life Care Planning After a Car Accident
A certified life care plan turns lifelong future needs into concrete, provable damages.
A life care plan is a written projection of the medical care, therapy, equipment, home changes and support services a seriously injured person will need for the rest of their life, with a cost attached to each item. The International Commission on Health Care Certification (ICHCC) describes the work as projecting those needs and their costs over the injured person’s remaining life span. In a Kentucky car accident case, the plan turns a general claim for future care into an itemized document a jury can check.
Certified Life Care Planners
A life care planner collects the medical, rehabilitation and home-environment facts of an injury and turns them into a lifetime schedule of care. The ICHCC practice standards say the planner must “project the need for such associated services and the costs of services, equipment, supplies, and medical/rehabilitative resources over the remaining life span” of the injured person.
The Certified Life Care Planner (CLCP) credential is the oldest and most widely held certification in the field, according to the ICHCC, which issues it. A candidate must be a health care professional and must complete 120 hours of approved training before sitting for the CLCP exam. Nurses with at least a nursing diploma and credentialed rehabilitation counselors can qualify. The ICHCC standards exclude licensed practical nurses and other technician-level licenses.
The finished plan lists each future need, how often it happens, how long it lasts and what it costs. The ICHCC standards say a life care plan rests on an in-person interview with the injured person, communication with providers, a review of the medical records and extensive medical research.
Injuries With Lasting Effects
The ICHCC ties the CLCP credential to people who have sustained “significant to catastrophic injury to one or multiple body systems.” A sprain that heals in a few weeks does not call for a lifetime plan. An injury with permanent effects often does.
A spinal cord injury is a clear example. Spinal cord damage can cause “temporary or permanent changes in feeling, movement, strength, and body functions” below the injury, according to the National Institute of Neurological Disorders and Stroke (NINDS). The same agency lists physical therapy, occupational therapy, vocational rehabilitation, braces and wheelchairs among the tools people use afterward, and each one can become a priced line in a plan.
Joint injuries create later costs too. Over a period of years, a hip prosthesis may wear out or loosen, and a painful loosening may require a second surgery called a revision, as OrthoInfo from the American Academy of Orthopaedic Surgeons explains. A plan for someone with a hip injury can account for that future operation. Traumatic brain injuries, amputations and severe burns are other injuries where a plan is often part of the case.
6 Categories of Future Care
Most plans group future needs into categories so each cost can be checked line by line. The ICHCC standards cover services, equipment, supplies and medical or rehabilitative resources. Broken out for a car accident injury, those needs sort into six groups:
- Surgeries and procedures: a hip revision if an implant loosens, scar revision after burns, removal of spinal hardware and other follow-up procedures a treating physician recommends.
- Therapy and rehabilitation: physical therapy, occupational therapy, cognitive rehabilitation after a brain injury, speech therapy and pain management programs, each with a projected number of visits and years.
- Medications and pain care: prescriptions, injection series and nerve blocks, with a yearly cost and an expected duration.
- Equipment and devices: wheelchairs, braces, prosthetics, orthotics and mobility aids, each with an expected lifespan and a replacement schedule.
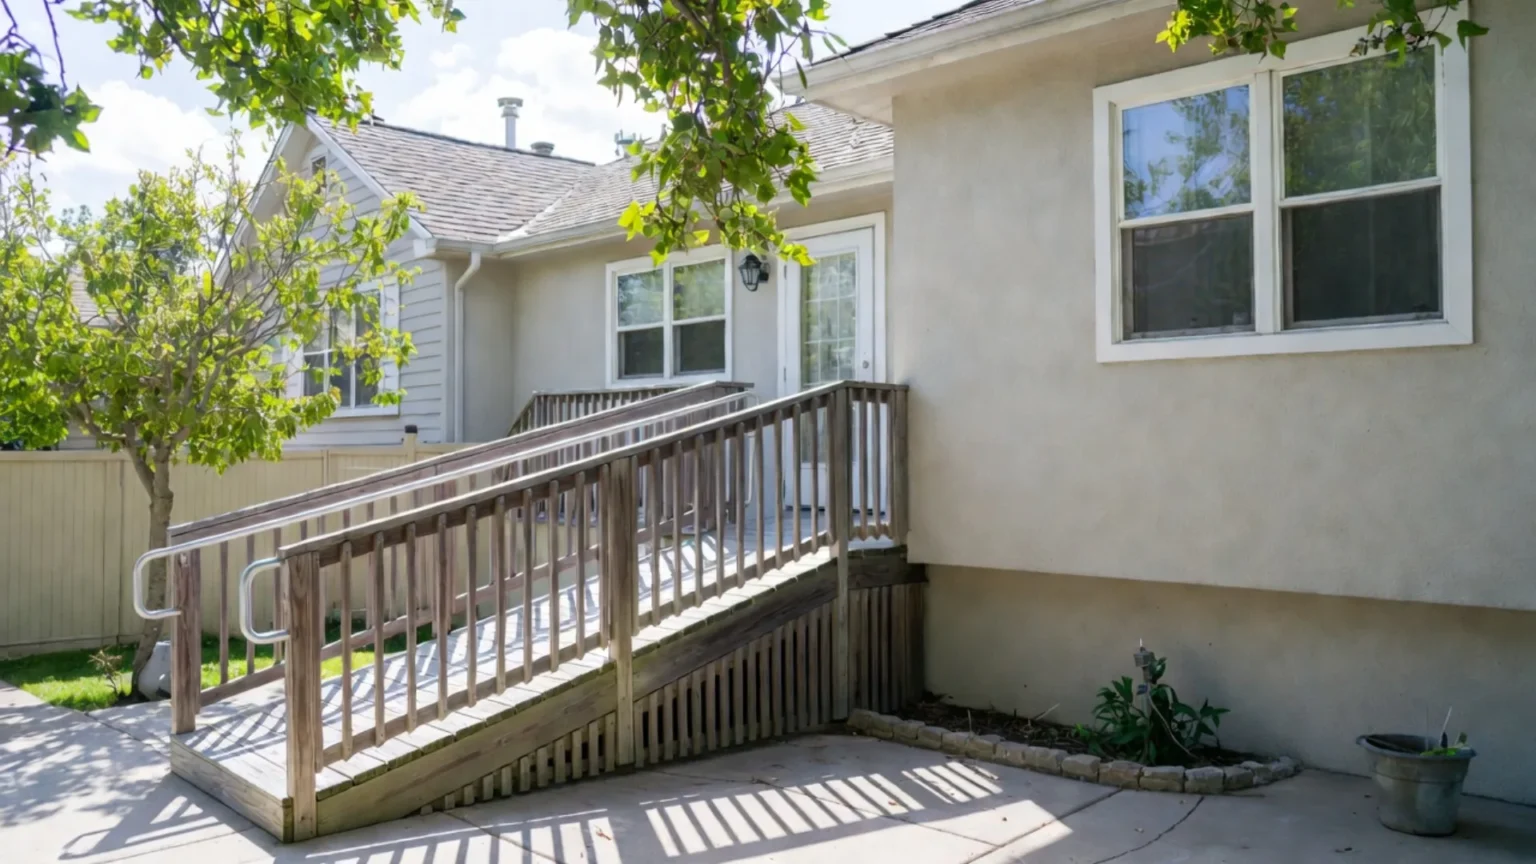
- Home and vehicle changes: ramps, bathroom changes, stair lifts, wider doorways and accessible vehicle conversions, plus upkeep for each.
- Attendant care and services: in-home nursing, personal care, respite care for family caregivers, rides to medical appointments and vocational rehabilitation when a return to modified work is possible.
Full Plans Versus Cost Projections
A medical cost projection and a life care plan both estimate future costs, but the ICHCC treats them as different products with different credentials.
A cost projection is based on a review of medical records covering part of the care, “in most cases, the last two years,” and the ICHCC calls it “a condensed, simplified abstract document.” A life care plan adds the in-person interview, provider communications and extensive medical research. On the question of which one belongs in a lawsuit, the ICHCC standards are direct: “the definitive product for the purpose of litigation and testimony is the life care plan.”
Kentucky Proof Rules for Future Damages
Kentucky juries can award future damages only when the evidence moves past a guess. In Rogers v. Sullivan, Kentucky’s highest court at the time said “the fact of damages must be taken out of the area of speculation,” and held that a qualified opinion grounded in probability meets that standard. The same opinion repeats the rule that proof of a permanent injury’s future effect “must be positive and satisfactory.”
A life care plan is built for that test. Each line ties a need to the medical records or a provider’s recommendation, sets a frequency and a duration, and attaches a cost. Without that detail, a request for “a lot of future medical care” is an estimate the other side can attack as speculation. With it, the claim becomes a list of specific therapies, devices and procedures for a specific number of years.
Car crash cases carry one more Kentucky gate. Unless the injured person filed a rejection of the tort limitation with the Department of Insurance before the crash, KRS 304.39-060 lets a plaintiff recover for “pain, suffering, mental anguish and inconvenience” only when medical expense benefits exceed $1,000 or the injury includes one of the listed conditions, such as a fracture, permanent disfigurement, permanent loss of bodily function or death. The statute also leaves some people outside the limit, including motorcycle passengers.
Economic and Non-Economic Damages
- Medical expense already paid or owed
- Wages already lost, documented through pay and tax records
- Future medical care, therapy and equipment supported by a qualified opinion
- Permanent impairment of the power to earn money, shown by positive and satisfactory evidence
- Pain, suffering, mental anguish and inconvenience
- A spouse’s loss of consortium, a separate claim under KRS 411.145
Sources: Rogers v. Sullivan, 410 S.W.2d 624 (Ky. 1967), KRS 304.39-020 (work loss), KRS 304.39-060 and KRS 411.145.
Testimony Under Kentucky Rule of Evidence 702
At trial, the planner can testify about how the plan was built and what each item costs. KRE 702 allows opinion testimony from a witness qualified “by knowledge, skill, experience, training, or education,” but only when the testimony is based on sufficient facts or data, comes from reliable principles and methods, and applies those methods reliably to the facts of the case.
Those three conditions are where a plan gets tested on cross-examination. A plan that skipped the records, left out the treating providers or priced care without research gives opposing counsel an opening. A plan that follows the ICHCC method and documents the source of every cost leaves far less to attack.
| Citation | Authority | Area |
|---|---|---|
| Citation410 S.W.2d 624 | Authority Rogers v. Sullivan (Ky. 1967) Holds that future damages must be taken out of the area of speculation and that a qualified opinion grounded in probability meets that standard. | AreaDamages |
| CitationKRS 304.39-060 | Authority Partial abolition of tort liability Sets the medical expense and injury threshold for recovering pain and suffering in a Kentucky motor vehicle case, unless the injured person filed a rejection of the tort limitation before the crash. | AreaDamages |
| CitationKRS 411.145 | Authority Damages for loss of consortium Lets a husband or wife recover from a negligent third person for loss of consortium. | AreaDamages |
| CitationKRE 702 | Authority Kentucky Rules of Evidence, Rule 702 Sets the conditions for opinion testimony from a witness qualified by knowledge, skill, experience, training or education. | AreaEvidence |
Source: the Kentucky Revised Statutes and Kentucky Rules of Evidence on the Kentucky General Assembly site, and the Rogers v. Sullivan opinion on CourtListener.
Starting Before Treatment Ends
The ICHCC standards say a life care plan is usually completed at the end of active treatment, after the injured person’s condition has stabilized. A cost projection, by contrast, can be done at the beginning of treatment or during it. That stable point is what physicians call maximum medical improvement, and it is also when a doctor assigns a permanent impairment rating.
Sam Aguiar Injury Lawyers brings a life care planner into catastrophic cases early, while treatment is still under way. The planner can follow the records as they arrive and talk with providers during care, then finish the plan once the person’s condition settles. The evidence for future damages is then ready before the demand goes out, not pieced together after.
Does a Lifelong Injury Need a Life Care Plan?
When an injury will need care for decades, the value of the claim depends on how well that future care is documented. Sam Aguiar Injury Lawyers brings in a certified life care planner while treatment is under way and builds the finished plan into the demand. Under our Bigger Share Guarantee®, you always walk away with more than the firm after bills, liens, and case costs. Start with a free case review.
Frequently Asked Questions
1What is a Certified Life Care Planner?+
2How is a life care plan different from a medical cost projection?+
3When is a life care plan used in a car accident case?+
4Does Kentucky require proof of future medical costs?+
5Can the other side challenge a life care plan?+
6When is a life care plan written?+
7Who pays for the life care planner?+
Latest Articles
Hip Injuries After a Car Accident
Hip injuries from a car accident, like acetabular fractures, carry long-term arthritis risk.
Loss of Consortium in Kentucky
Spouses can recover under KRS 411.145, and Kentucky case law adds claims for minor children, when a serious injury changes the family.
Treatment Gaps After Car Accidents
A gap in treatment after a wreck does not end the case, but it changes how the records are read.