

Personal Injury Insurance Claim Reserves
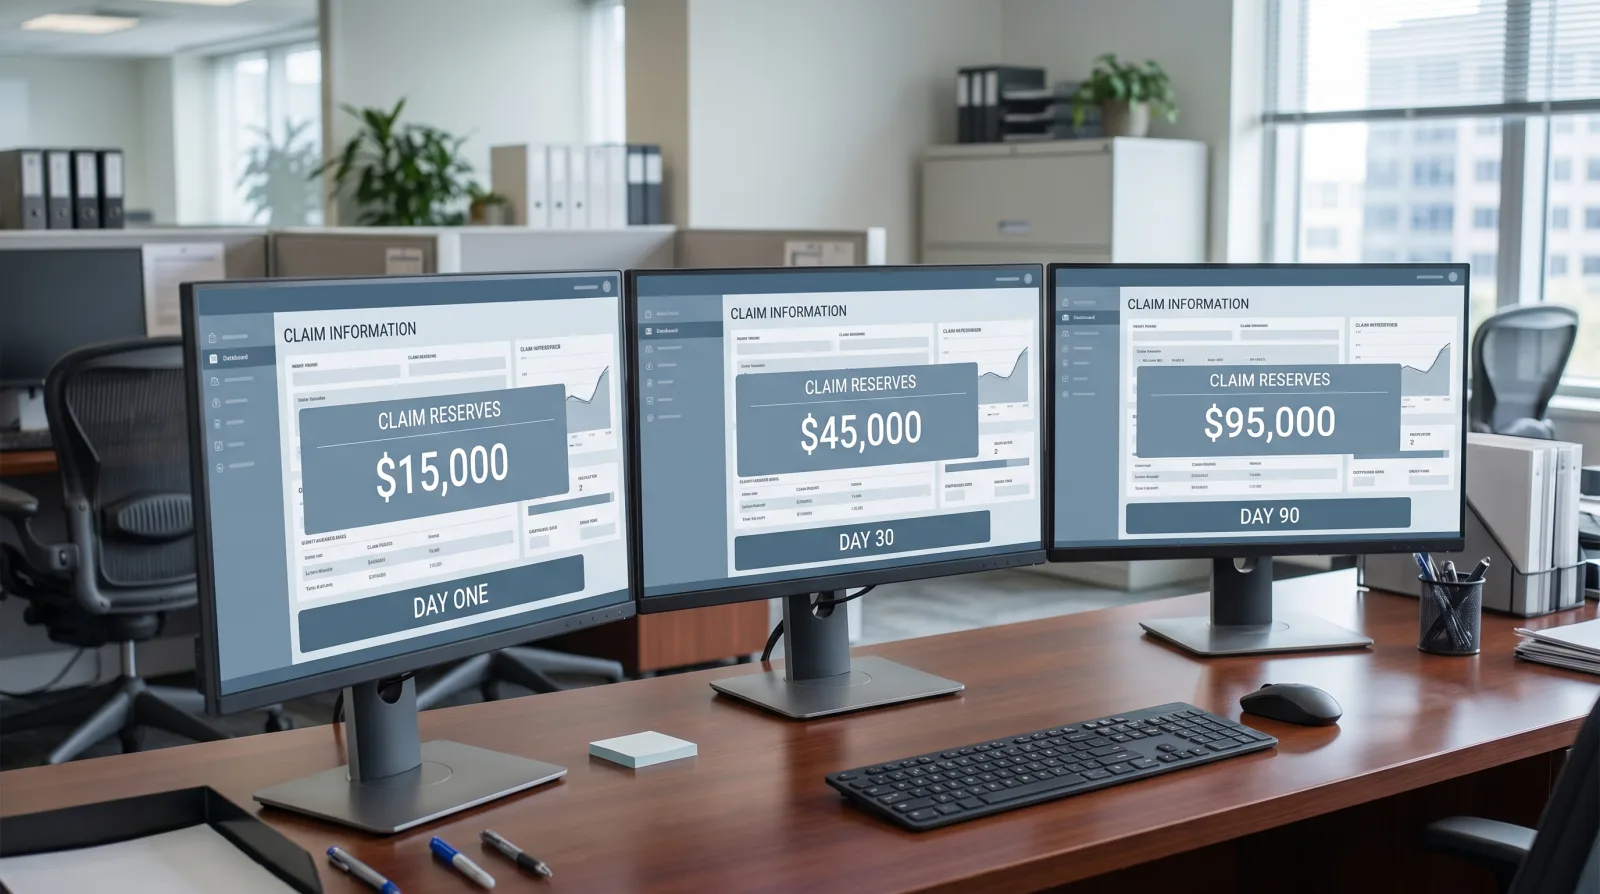
A claim reserve is money an insurer books for a loss that has already happened and is not fully paid. On a personal injury file, the figure tied to the claim is usually the case reserve: the insurer’s current estimate of what the file will cost. That estimate can change many times before the claim closes, and it sets no ceiling on what the injured person can recover.
Case Reserve Function
A case reserve is assigned to one reported claim. It can include expected indemnity and loss-adjustment expense as the carrier currently sees the file. The initial reserve is often set at first notice of loss, based on limited information such as the type of crash and the vehicle damage, so early reserves can be conservative.
The number moves when medical records, liability facts, or litigation posture change. A later increase does not show that the first number was unlawful, and a later decrease does not show that the injury improved.
The National Association of Insurance Commissioners annual statement instructions treat case reserves as amounts set on individual claims, separate from bulk and IBNR reserves. That is an accounting split. No Kentucky statute uses it to tell an adjuster what to offer.
IBNR and Bulk Reserves
IBNR (incurred but not reported) reserves cover losses that have happened but are not yet in a case file, plus development that has not been assigned to a specific claim. Bulk reserves can also sit on claims that already carry a case reserve, when actuaries expect the booked number to grow. Those book-level estimates explain how a company can look adequately reserved on its annual statement while one injury file still looks thin.
Reserve adequacy in that financial sense measures the insurer’s unpaid-claim liability in the aggregate. Kentucky has no rule requiring a particular dollar case reserve on an individual injury file.
Claims Handling Duties Under KRS 304.12-230
KRS 304.12-230, Kentucky’s Unfair Claims Settlement Practices Act, lists 17 prohibited acts. Among them are failing to act promptly on claim communications, failing to adopt standards for prompt investigation, failing to affirm or deny coverage within a set time after proof of loss statements are completed, failing to attempt a good-faith settlement once liability has become clear, and failing to explain the basis for a denial or a compromise offer. None of the 17 acts mentions a case reserve.
A low case reserve can still sit next to a slow investigation, a missing explanation, or an offer that ignores a complete medical file. Those claims-handling facts are shown through the claim correspondence and the medical records. The full list of prohibited acts is covered in unfair claims and settlement practices.
Some carriers also run valuation software such as Colossus, which assigns severity points to injuries and treatment and applies dollar values the carrier sets internally. Kentucky’s insurance code does not describe those programs, and the scoring a carrier will not produce is not a public fact. The public duties remain the investigation, explanation, and settlement rules in the statute.
Settlement Authority Limits
Adjusters often work inside a dollar band that the carrier ties to the file. That band can track the case reserve, sit below it, or require a supervisor once an offer approaches the booked number. Those are company procedures, and Kentucky law does not treat them as a cap on recoverable damages.
The policy limits, the medical records, and the liability facts set what a claim can support. A case reserve that never moved after surgery records arrived may be evidence of how the file was handled, but the reserve alone does not measure the injury. KRS 304.20-045 separately bars an insurer from raising a premium solely because of a claim when the insured was not at fault.
Evidence That Moves a Reserve
Well-documented evidence gives an adjuster a reason to revise a reserve upward, which also raises settlement authority:
- Medical records documenting severe or permanent injuries, such as fractures, herniated discs, spinal cord damage, traumatic brain injury, and soft-tissue damage requiring surgery.
- Future medical cost projections, meaning a treating provider’s documented opinion about ongoing treatment needs and expected costs.
- Economic loss documentation, including wage verification, tax records, and employer statements about missed work.
- Liability evidence, including police reports, witness statements, and crash reconstruction analysis.
- Evidence of egregious conduct, such as impaired driving or hours-of-service violations in a truck case, which can open the door to punitive damages.
A claim sitting open at a low reserve creates little internal pressure to settle, which is one reason reserve practices connect to insurance payment delays and the adjuster tactics used on a Kentucky car accident claim.
Ready to Take Action on Your Injury Claim?
After a serious injury, medical bills pile up while the insurance company looks for ways to pay you less. Most law firms take their cut first and leave you with whatever is left. Sam Aguiar Injury Lawyers does things differently. With our exclusive Bigger Share Guarantee®, you always get more. Every client gets a dedicated three-person team: an attorney, a case manager, and a legal assistant. We never raise our fee rate if we have to go to court, and you pay $0 Out-Of-Pocket Forever.
Frequently Asked Questions
1Is the case reserve the most an injury claim can pay?+
2What is the difference between a case reserve and IBNR?+
3Does Kentucky law require the insurer to disclose the reserve?+
4Can a not-at-fault claim raise the injured person’s own premium?+
5Does valuation software decide the claim?+
Latest Articles

Kentucky Diminished Value Claims
Kentucky drivers may pursue a repaired vehicle’s leftover market loss from the at-fault driver as part of a.

FMCSA Revoked ELDs: Fleet Compliance and Enforcement Deadlines
FMCSA removed five electronic logging devices from the registered list on August 6, 2026, and set an October.

FMCSA English Proficiency Rule and OOS Enforcement
FMCSA English Proficiency Rule Sam Aguiar Injury Lawyers August 11, 2026 7 minute read On This Page.