Life Care Planning After a Car Accident
A certified life care plan turns lifelong future needs into concrete, provable damages.
Key Takeaways
- A life care plan is a line-by-line projection of every treatment, therapy, device, and support service an injured person will need for life.
- It is prepared by a Certified Life Care Planner (CLCP), who can also testify at trial to support the projected costs.
- Retaining a life care planner early strengthens the claim and helps it withstand insurance-company challenges.
Life Care Planner Role
A life care plan is a detailed, line-by-line projection of every medical treatment, therapy, device, home modification, and support service an injured person will need for the rest of their life. Created by a Certified Life Care Planner (CLCP), it converts abstract “future damages” into a concrete document with specific costs. In catastrophic car accident claims, a well-built life care plan is often the single most important piece of evidence for full recovery.
A life care planner is a certified medical professional, most often a registered nurse who holds the Certified Life Care Planner (CLCP) credential issued by the International Commission on Health Care Certification (ICHCC). Their job is to review your medical records, consult with your treating physicians, and build a complete projection of every category of care you will need going forward.
The result is not a guess. It is a structured document that lists each future need, the frequency, the duration, and the projected cost range based on current medical pricing in your geographic area. It becomes a roadmap for your future care and the financial foundation of your claim.
When a Life Care Plan Is Needed
Not every car accident case requires a life care plan. It is used when the injuries have lifelong implications that extend well beyond current treatment. These include:
Life care plans are also critical for hip injuries requiring future revision surgeries, amputations with prosthetic replacement cycles, and any injury with permanent functional limitations that will require ongoing treatment for decades.
Life Care Plan Contents
A thorough life care plan covers every category of future need. The CLCP builds each section by reviewing your medical records, interviewing your treating physicians, and applying evidence-based projections for cost and duration. According to the ICHCC professional standards, every item must be supported by medical documentation and physician recommendations.
- Future Surgeries and Procedures
Hip revision in 15 to 20 years, scar revisions for burns, spinal hardware removal, and follow-up procedures the treating physician has recommended or that medical literature supports as likely needed.
- Ongoing Therapy and Rehabilitation
Physical therapy, occupational therapy, cognitive rehabilitation for TBI, speech therapy, and pain management programs projected over the expected duration of need.
- Medications and Pain Management
Prescriptions, injection series, nerve blocks, and other pain management modalities with projected annual costs and expected duration.
- Assistive Devices and Equipment
Wheelchairs, prosthetics with replacement cycles, adaptive equipment, orthotics, and mobility aids. Each item has a projected lifespan and replacement schedule.
- Home and Vehicle Modifications
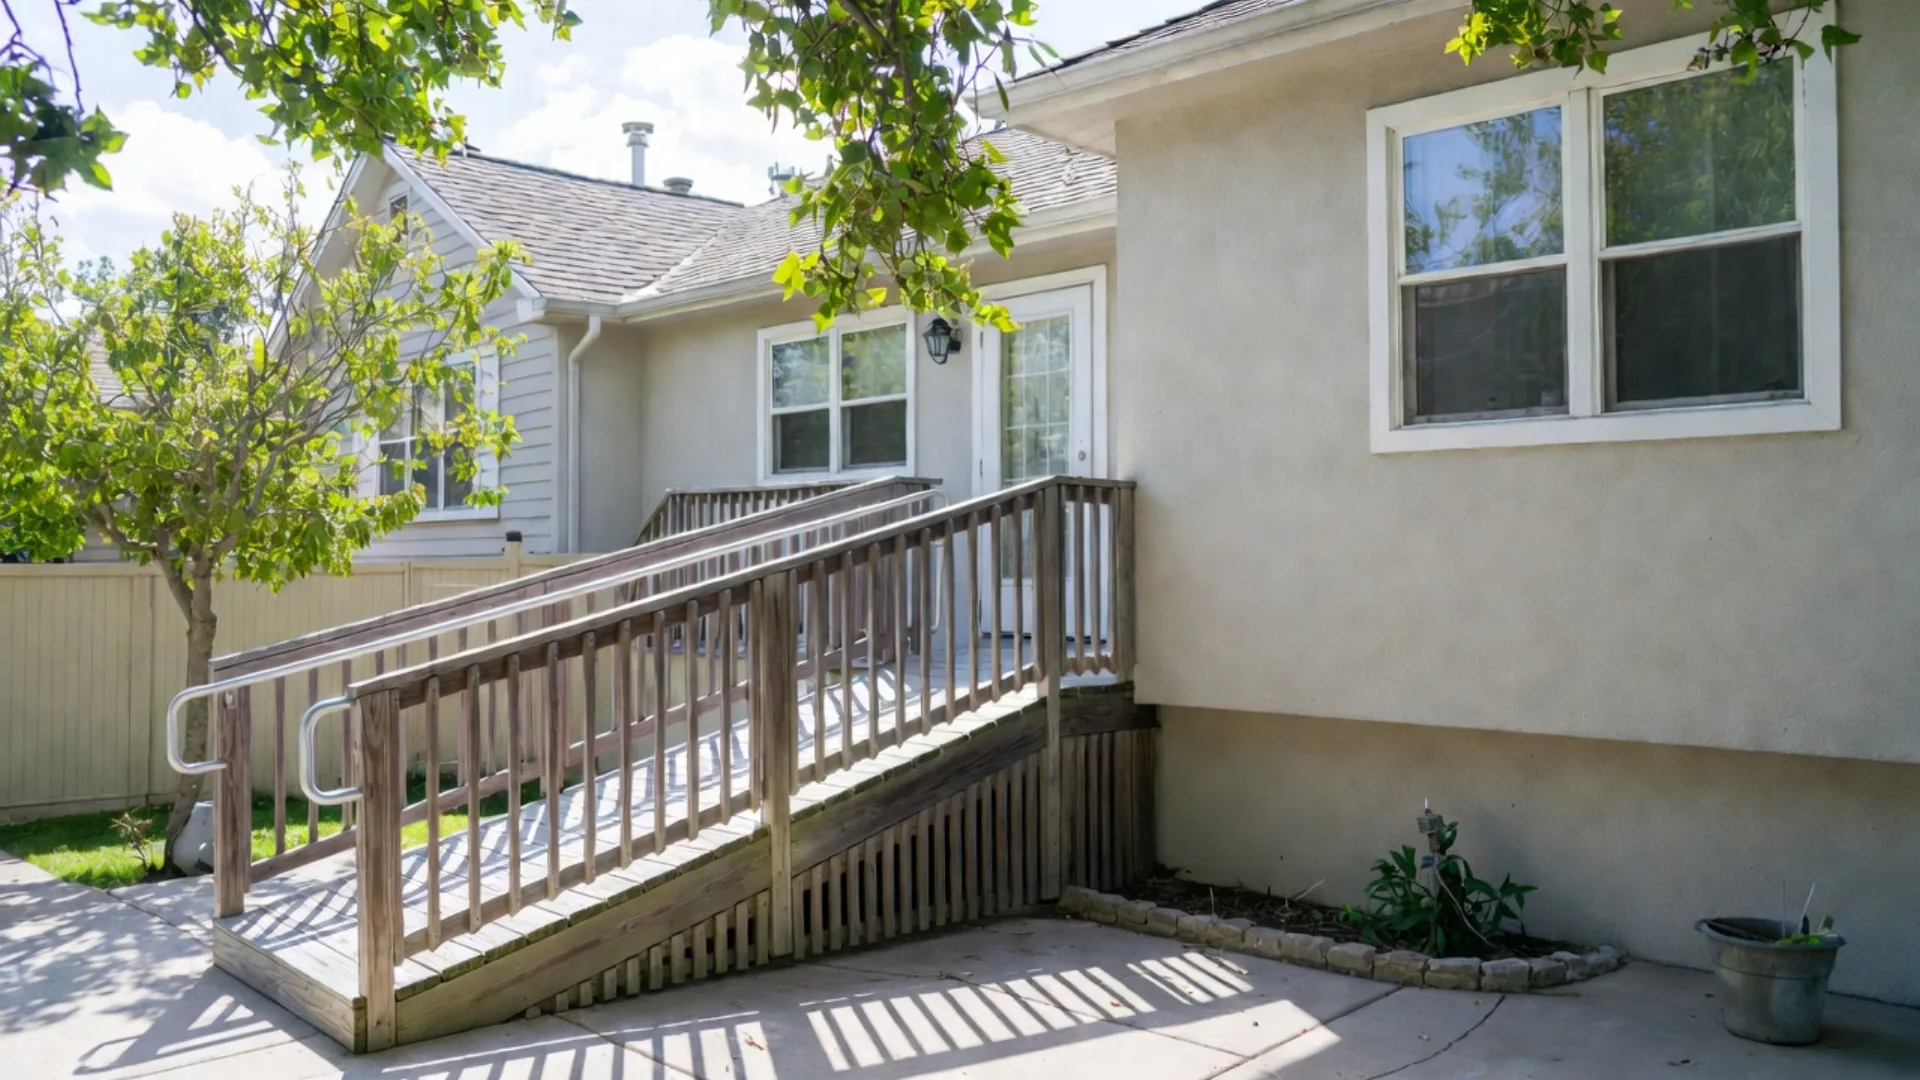
Wheelchair ramps, bathroom modifications, stair lifts, widened doorways, accessible vehicle conversions, and maintenance schedules for all modifications.
- Attendant Care and Support Services
In-home nursing care, personal care support, respite care for family caregivers, transportation to medical appointments, and vocational rehabilitation if the person can return to work in a modified capacity.
How a Life Care Plan Strengthens Your Claim
Without a life care plan, future damages are an estimate. The insurance company’s adjuster will argue the number is speculative, inflated, or unsupported. A properly built life care plan changes that dynamic entirely.
Each item in the plan is tied to a specific medical recommendation, a specific cost range based on local pricing data, and a specific duration based on the injured person’s life expectancy and medical literature. When the adjuster asks “where did you get that number?” the answer is a 40-page document with physician sign-offs, cost research, and evidence-based projections.
Think of it this way: telling an insurance company you will need “a lot of future medical care” is easy to dismiss. Presenting a life care plan showing that a 35-year-old with a spinal cord injury will need specific therapies at specific frequencies for the next 45 years, with line-item costs for each, is much harder to argue against. The plan converts a vague claim into an itemized demand.
The Life Care Planner at Trial
If the case goes to trial, the life care planner testifies as a qualified experienced witness. They walk the jury through every category of the plan, explain the medical basis for each item, and present the cost projections. Their testimony is grounded in their clinical background, their review of the medical records, their consultations with treating physicians, and the professional standards set by the ICHCC.
The insurance company will typically retain their own life care planner to dispute the projections. This is why the quality of the initial plan matters. A plan built by a credentialed CLCP who followed established methodology and documented every source is much harder to undermine on cross-examination than one built without that rigor.
We Retain Life Care Planners Early
At Sam Aguiar Injury Lawyers, we bring in a life care planner early in every catastrophic case. The reason is straightforward: if we wait until the demand stage to project future needs, we are working backwards. By retaining the planner while the client is still in active treatment, the planner can observe the care firsthand, consult with treating physicians in real time, and build a plan that reflects the full trajectory of recovery.
This is one of the reasons our average case resolution is under 7 months. We build the evidence before we need it, not after.
What Damages Can I Recover After an Injury?
After an injury, damages come in two forms: economic and non-economic. They are designed to make a victim whole for out-of-pocket losses and to compensate them for the physical and emotional tolls that come with the injuries.
Frequently AskedQuestions.
What is a Certified Life Care Planner (CLCP)?
How much does a life care plan cost?
When is a life care plan used in a car accident case?
Can the insurance company challenge a life care plan?
What is the difference between a life care plan and a medical cost projection?
Does a life care planner testify in court?
How early should a life care planner be retained in a case?
Chest Injuries From a Kentucky Car Accident
Updated August 5, 2026
Internal Organ Injuries From a Kentucky Car Accident
Updated August 5, 2026
Car Accident Shoulder Injuries
Updated August 5, 2026
Facial Injuries From a Kentucky Car Accident
Updated August 5, 2026