

Do I Need a Lawyer After a Car Accident That Wasn’t My Fault?
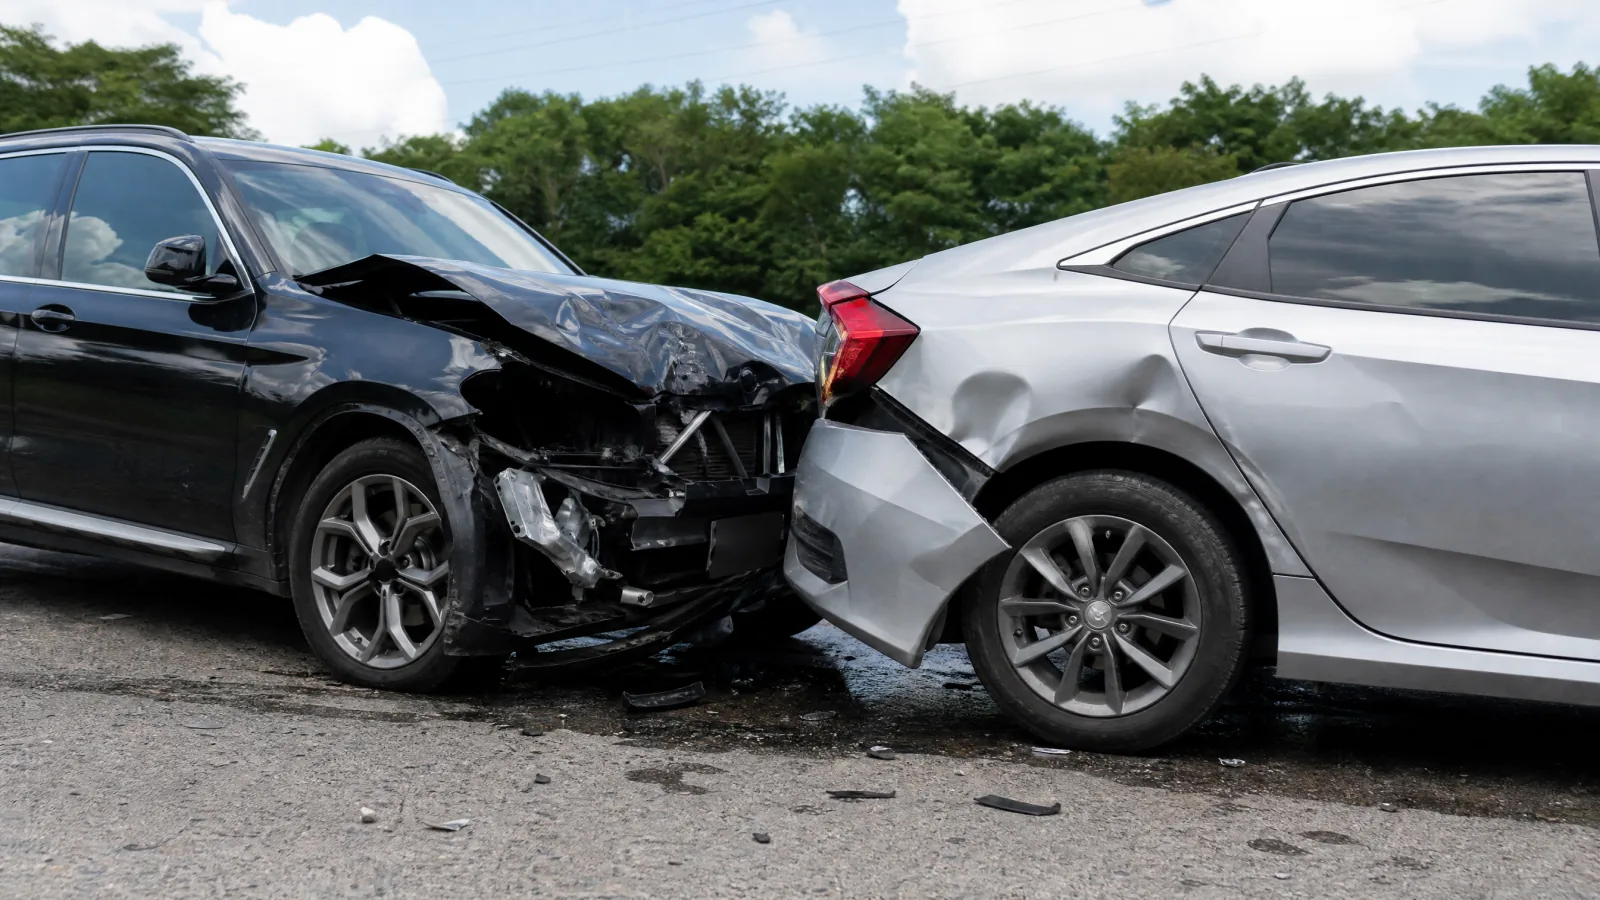
An at-fault driver’s insurer owes an injured person nothing automatically. It pays when liability is established, damages are documented, and a settlement or judgment sets the number, and until then every bill that arrives is the injured person’s problem. Kentucky adds a layer most states do not have: as a choice no-fault state under KRS 304.39-060, the injured person’s own policy is the first payer for medical bills and lost wages even when the other driver is entirely at fault. Being not at fault changes who ultimately reimburses the loss. Who pays first, how fast the money moves, and how hard the at-fault insurer works to close the claim cheaply stay the same.
Personal Injury Protection Pays First
Kentucky’s no-fault system runs on personal injury protection, usually called PIP. Under KRS 304.39-020, basic reparation benefits provide $10,000 per person, per accident, for medical expenses, lost wages, and replacement services. The benefits come from the policy covering the vehicle the injured person occupied, and they pay without regard to fault. When a driver runs a red light and causes an accident, the first $10,000 in accident bills still runs through PIP.
Many drivers find this backwards. The design moves money to injured people within weeks, compared with the months or years a liability claim takes. In exchange, Kentucky limits lawsuits for pain and suffering unless the injury crosses the threshold in KRS 304.39-060: at least $1,000 in medical expenses, a broken bone, permanent disfigurement, permanent injury, or death. Injuries serious enough to need a lawyer almost always clear it.
PIP can reach beyond the basic $10,000. Kentucky insurers offer added reparation benefits that raise the coverage, as explained in added PIP coverage in Kentucky, and rejecting PIP creates its own problems. The more PIP available, the less pressure an injured person feels to take the at-fault insurer’s first offer while bills pile up.
PIP paid out on a not-at-fault claim does not simply disappear from the injured person’s coverage. The paying carrier recovers much of it from the at-fault driver’s insurer through reimbursement rights built into the statute.
Medical Bills During an Open Claim
The gap between an accident and a settlement is where unrepresented people struggle most. Treatment and hospital billing start immediately, while the at-fault insurer’s payment arrives once, at the end, after negotiations close.
PIP pays medical providers as bills come in, and Kentucky law gives the injured person meaningful control over how, a topic covered in directing PIP payments in Kentucky. Spent carelessly, $10,000 in PIP disappears into the first emergency room invoice. Directed deliberately, it keeps a treating physician, physical therapist, and imaging provider engaged while the injury claim develops.
Hospital care raises its own problems: emergency room liens, out-of-network charges, and billing departments that would rather bill the accident claim than health insurance, as covered in going to the hospital after an accident. Every dollar of medical billing handled sloppily while the claim is open comes out of the final recovery, and a messy medical record is easier for the at-fault insurer to dispute.
Explanation-of-benefits statements, bills, and receipts for out-of-pocket costs, including mileage to appointments and pharmacy charges, belong in one place from the first week. Small documented losses add up, and undocumented ones drop out of the claim.
Once PIP is exhausted, health insurance should take over as the payer for accident treatment, and most plans then assert a right of repayment out of the settlement. Those repayment claims are negotiable, and negotiating them down line by line is one way represented claimants keep more of a settlement.
Lost Wages and Earning Capacity
Missed shifts, exhausted sick leave, and a body that cannot do the job it did before often cost more than the medical bills, starting in the first week. Kentucky’s answer again begins with PIP. House Bill 627 raised the weekly cap on work loss benefits from $200 to $500 for policies issued or renewed on or after July 15, 2026, a change covered in Kentucky PIP coverage.
Income loss above the PIP benefit belongs in the bodily injury claim against the at-fault driver. Documenting it takes more than a pay stub: employer records, tax returns for variable earners, and treating-physician work restrictions that connect the missed income to the injury. Self-employed people and commission earners lose the most when this is handled casually, because their income is the easiest for an adjuster to dispute and the hardest to reconstruct later.
Future income carries even more weight. When an injury permanently limits the work a person can do, lost earning capacity is part of the claim, and insurers resist it hardest because it carries the largest numbers. It also cannot be reopened after a release is signed.
Bodily Injury Settlement Coverage
The claim against the at-fault driver, called a bodily injury claim, is where most of the recovery comes from. It covers what PIP does not: medical expenses beyond the PIP limits, lost income beyond the PIP wage benefit, pain and disruption, future treatment, and permanent limitations. Once the threshold is met, Kentucky law places every category of loss the accident caused on the at-fault side.
A demand goes out when treatment reaches a stable point, supported by the complete medical record, the wage documentation, and the liability evidence. The insurer responds low, the gap narrows across rounds, and the file either settles or goes to suit. Insurers also track which firms file lawsuits, and the same injury draws different offers depending on who signs the demand letter.
The bodily injury settlement arrives once, with a release. Signing it ends the claim permanently, regardless of what the injury does the following year. The insurer’s goal is a release signed early, while the medical picture is incomplete and the claimant is tired of the process, and that single fact explains most of what goes wrong in unrepresented claims.
Property Damage, Rentals, and Diminished Value
The vehicle claim is usually the first negotiation with the at-fault insurer, and it sets the tone for everything after. There are two routes to a repaired or replaced vehicle: the at-fault driver’s property damage coverage, or the injured person’s own collision coverage, with the deductible recovered later through subrogation. The at-fault route costs nothing upfront but moves only as fast as the insurer’s liability decision. The collision route moves immediately. When liability is contested or the other insurer is slow, the collision route is often the practical choice, as explained in Kentucky property damage claims.
Insurers often settle vehicles quickly, because a closed property claim feels like progress and builds a relationship with an unrepresented claimant before the injury conversation starts. Total-loss valuations come from vendor databases whose comparable vehicles can be challenged line by line on mileage, trim, condition, and local market. Rental coverage runs only for a defined period, and a properly repaired newer vehicle is still worth less on resale than one that was never hit. That diminished value is a real part of a Kentucky property claim.
Accepting a property settlement does not settle the injury claim. The two claims share an accident and nothing else.
Liability Evidence
An obvious-seeming fault question still needs evidence. The police report is a starting point that adjusters rely on, but it is one officer’s after-the-fact reconstruction, written at a chaotic scene, sometimes from nothing more than two competing accounts. Reports contain errors and officers miss witnesses, and when a report is thin or wrong, the at-fault insurer treats fault as an open question because a disputed claim is a cheaper claim.
Liability evidence includes photographs of the vehicles and scene, damage patterns that show angle and force, witness statements gathered before memories fade, vehicle data, and video. Modern cars record data that can establish speed and braking in the seconds before impact, as covered in delta-v and crash forces. Businesses record over surveillance footage within days, and traffic camera archives expire.
Sam Aguiar Injury Lawyers has direct access to six-month rolling archives of DOT and TRIMARC traffic camera footage. When fault is contested at a Louisville intersection or on a Lexington corridor, footage of the accident itself settles the argument, identifies hit-and-run drivers, and resolves disputes over whose light was green.
Fault Patterns in Common Accident Types
Some accidents carry a presumption of fault. A rear-end impact points at the trailing driver, who owed the distance and attention. A left turn across oncoming traffic points at the turning driver, who owed the yield. Running a light or stop sign, drifting across a center line, and backing into traffic each come with a default answer that adjusters, judges, and juries recognize. In those accidents, the dispute usually moves from who caused the accident to the injuries it caused.
Other accidents invite a liability contest. Lane-change sideswipes turn into disputes over who drifted. Intersection accidents with no camera and no independent witness come down to which driver sounds more certain. Parking lot accidents happen on private property at low speeds, where police often decline to assign fault. Multi-vehicle chain reactions on the interstate spread fault across several drivers, and every insurer involved sees an opening to discount its share. In these cases, the evidence is the case.
Impact severity is the at-fault insurer’s favorite fallback once liability is settled. A low-speed impact with modest bumper damage becomes “nobody could have been hurt in that,” an argument that ignores how occupant injury relates to crash forces, vehicle geometry, and body position. Answering it takes vehicle data, repair records, and treating physicians who connect the mechanism to the diagnosis, and it is far easier when the vehicle was documented before repair.
Weather and road conditions cut both ways. Kentucky law still expects drivers to match their speed to conditions, so losing control on ice is usually a following-too-fast problem. Construction zones, missing signage, and defective road design occasionally add a government or contractor defendant, which is another coverage source.
Commercial Coverage for Working Drivers
When the at-fault driver was on the clock (delivering packages, driving a rideshare fare, hauling for a company, or running an errand for an employer), the claim usually reaches past the driver’s personal policy and into commercial coverage. Commercial policies carry higher limits, a difference that decides serious-injury cases where a personal policy at Kentucky’s minimum would not come close to covering the harm.
Employer liability is rarely volunteered. The driver may not mention the job, and the adjuster handling the personal auto policy has no reason to point to a second, larger policy. Finding the commercial coverage takes investigation into the vehicle registration, what the driver was doing at that moment, whether a delivery app was running, and the actual employment relationship. Delivery companies often classify drivers as independent contractors, a structure examined in the Amazon DSP contractor model and rising Amazon delivery accidents.
Fleet vehicles also carry telematics such as GPS trails, speed logs, and sometimes inward- and outward-facing cameras. That data is preserved when a lawyer demands it early and overwritten when nobody does. None of this requires a semi truck: a pizza delivery sedan, a landscaping crew pickup, or a home-health aide between appointments can all have commercial coverage behind them.
Uninsured and Hit-and-Run Drivers
Kentucky requires every motor vehicle owner to carry liability coverage of at least $25,000 per person and $50,000 per accident for bodily injury, plus $25,000 for property damage, according to the Kentucky Transportation Cabinet, with the minimum limits set in KRS 304.39-110. Some drivers carry nothing anyway, and many serious injuries exceed a $25,000 policy several times over.
When the at-fault driver is uninsured, flees the scene, or carries too little coverage, the injured person’s own policy steps back in. Uninsured motorist coverage stands in for the missing liability policy, and underinsured motorist coverage sits on top of an inadequate one. The injured person’s insurer defends both claims like any liability carrier would. PIP still pays first after a hit-and-run in Kentucky, and an uninsured motorist claim can still produce a full recovery, but the sequencing is less forgiving of mistakes.
Households with multiple vehicles may be able to stack uninsured and underinsured motorist coverage, depending on how the policies were written. Coverage decisions made before the accident, including PIP levels, uninsured motorist limits, and stacking elections, set the ceiling on some of these claims.
Duties and Protections With the Claimant’s Own Insurer
A not-at-fault claim puts the injured person in front of two insurance companies. For PIP, the injured person’s own insurer is a payer with statutory duties and deadlines. For an uninsured or underinsured motorist claim, that same insurer becomes the opposing party, evaluating the injury with the same incentive to pay less.
The policy also imposes duties on the insured: notice of the accident, cooperation with the carrier’s investigation, and making the vehicle available for inspection. Missing those conditions is one of the few ways a clean claim gets damaged.
Kentucky gives claimants protection when an insurer drags its feet. The Unfair Claims Settlement Practices Act, KRS 304.12-230, makes it an unfair practice to fail to attempt a good-faith settlement once liability has become reasonably clear, and Kentucky courts allow bad faith claims against carriers that cross that line.
Passenger Claims
Passengers are the clearest not-at-fault claimants on the road, and often the most confused about where to turn. A passenger’s PIP comes first from the policy on the vehicle they occupied, and the passenger’s bodily injury claim runs against whichever driver caused the accident. In a two-car accident, that can mean a claim against the other driver, against the passenger’s own driver, or against both, and none of it requires the passenger to own a car or carry insurance.
Claims against a friend or family member who was driving feel uncomfortable, and that discomfort keeps injured passengers from pursuing coverage the driver’s premiums already paid for. The claim runs against a policy priced and sold for exactly this event. Passengers hurt in a household member’s vehicle can also run into a PIP rejection problem, where one person’s rejection reaches further than anyone in the house realized, a trap explained in Kentucky PIP coverage.
Children injured as passengers add court-approval requirements to the claim, and serious passenger injuries in multi-vehicle accidents can involve three or four insurers at once, each pointing at the others.
Pedestrians, Cyclists, and Motorcyclists
A pedestrian struck in a crosswalk or a cyclist hit in a bike lane did nothing that belongs in an insurance negotiation, yet these claims draw some of the most aggressive defense treatment in the system, because the injuries are severe and the payouts follow. Kentucky’s no-fault structure still applies: a pedestrian struck by a motor vehicle generally draws PIP benefits even without owning a car or a policy, and the liability claim proceeds against the driver on top of it. More on these claims is in pedestrian accident claims.
Motorcyclists live under different rules. PIP does not automatically cover motorcycle riders the way it covers car occupants, and motorcycle PIP is a separate purchase many riders decline, so an injured rider often has no first-payer cushion while the liability claim develops. The bills arrive with nothing to absorb them, and early low offers land on the people with the least room to refuse them, as covered in motorcycle accident claims.
Adjusters, and sometimes police reports, start from the assumption that the person outside the car came out of nowhere. Camera footage, scene measurement, and vehicle data answer that assumption. Drivers also owe heightened care where children are present, and school zones carry their own duties.
Ready to Take Action on Your Injury Claim?
After a serious injury, medical bills pile up while the insurance company looks for ways to pay you less. Most law firms take their cut first and leave you with whatever is left. Sam Aguiar Injury Lawyers does things differently. With our exclusive Bigger Share Guarantee®, you always get more. Every client gets a dedicated three-person team: an attorney, a case manager, and a legal assistant. We never raise our fee rate if we have to go to court, and you pay $0 Out-Of-Pocket Forever.
Frequently Asked Questions
1If the accident clearly was not my fault, why does my own insurance pay first?+
2When does the at-fault driver’s insurance start paying?+
3What if the at-fault driver does not have enough insurance?+
4Does clear fault mean no evidence is needed?+
5What happens if the at-fault driver has no insurance at all?+
Latest Articles

Kentucky Diminished Value Claims
Kentucky drivers may pursue a repaired vehicle’s leftover market loss from the at-fault driver as part of a.

FMCSA Revoked ELDs: Fleet Compliance and Enforcement Deadlines
FMCSA removed five electronic logging devices from the registered list on August 6, 2026, and set an October.

FMCSA English Proficiency Rule and OOS Enforcement
FMCSA English Proficiency Rule Sam Aguiar Injury Lawyers August 11, 2026 7 minute read On This Page.