

Kentucky Diminished Value Claims
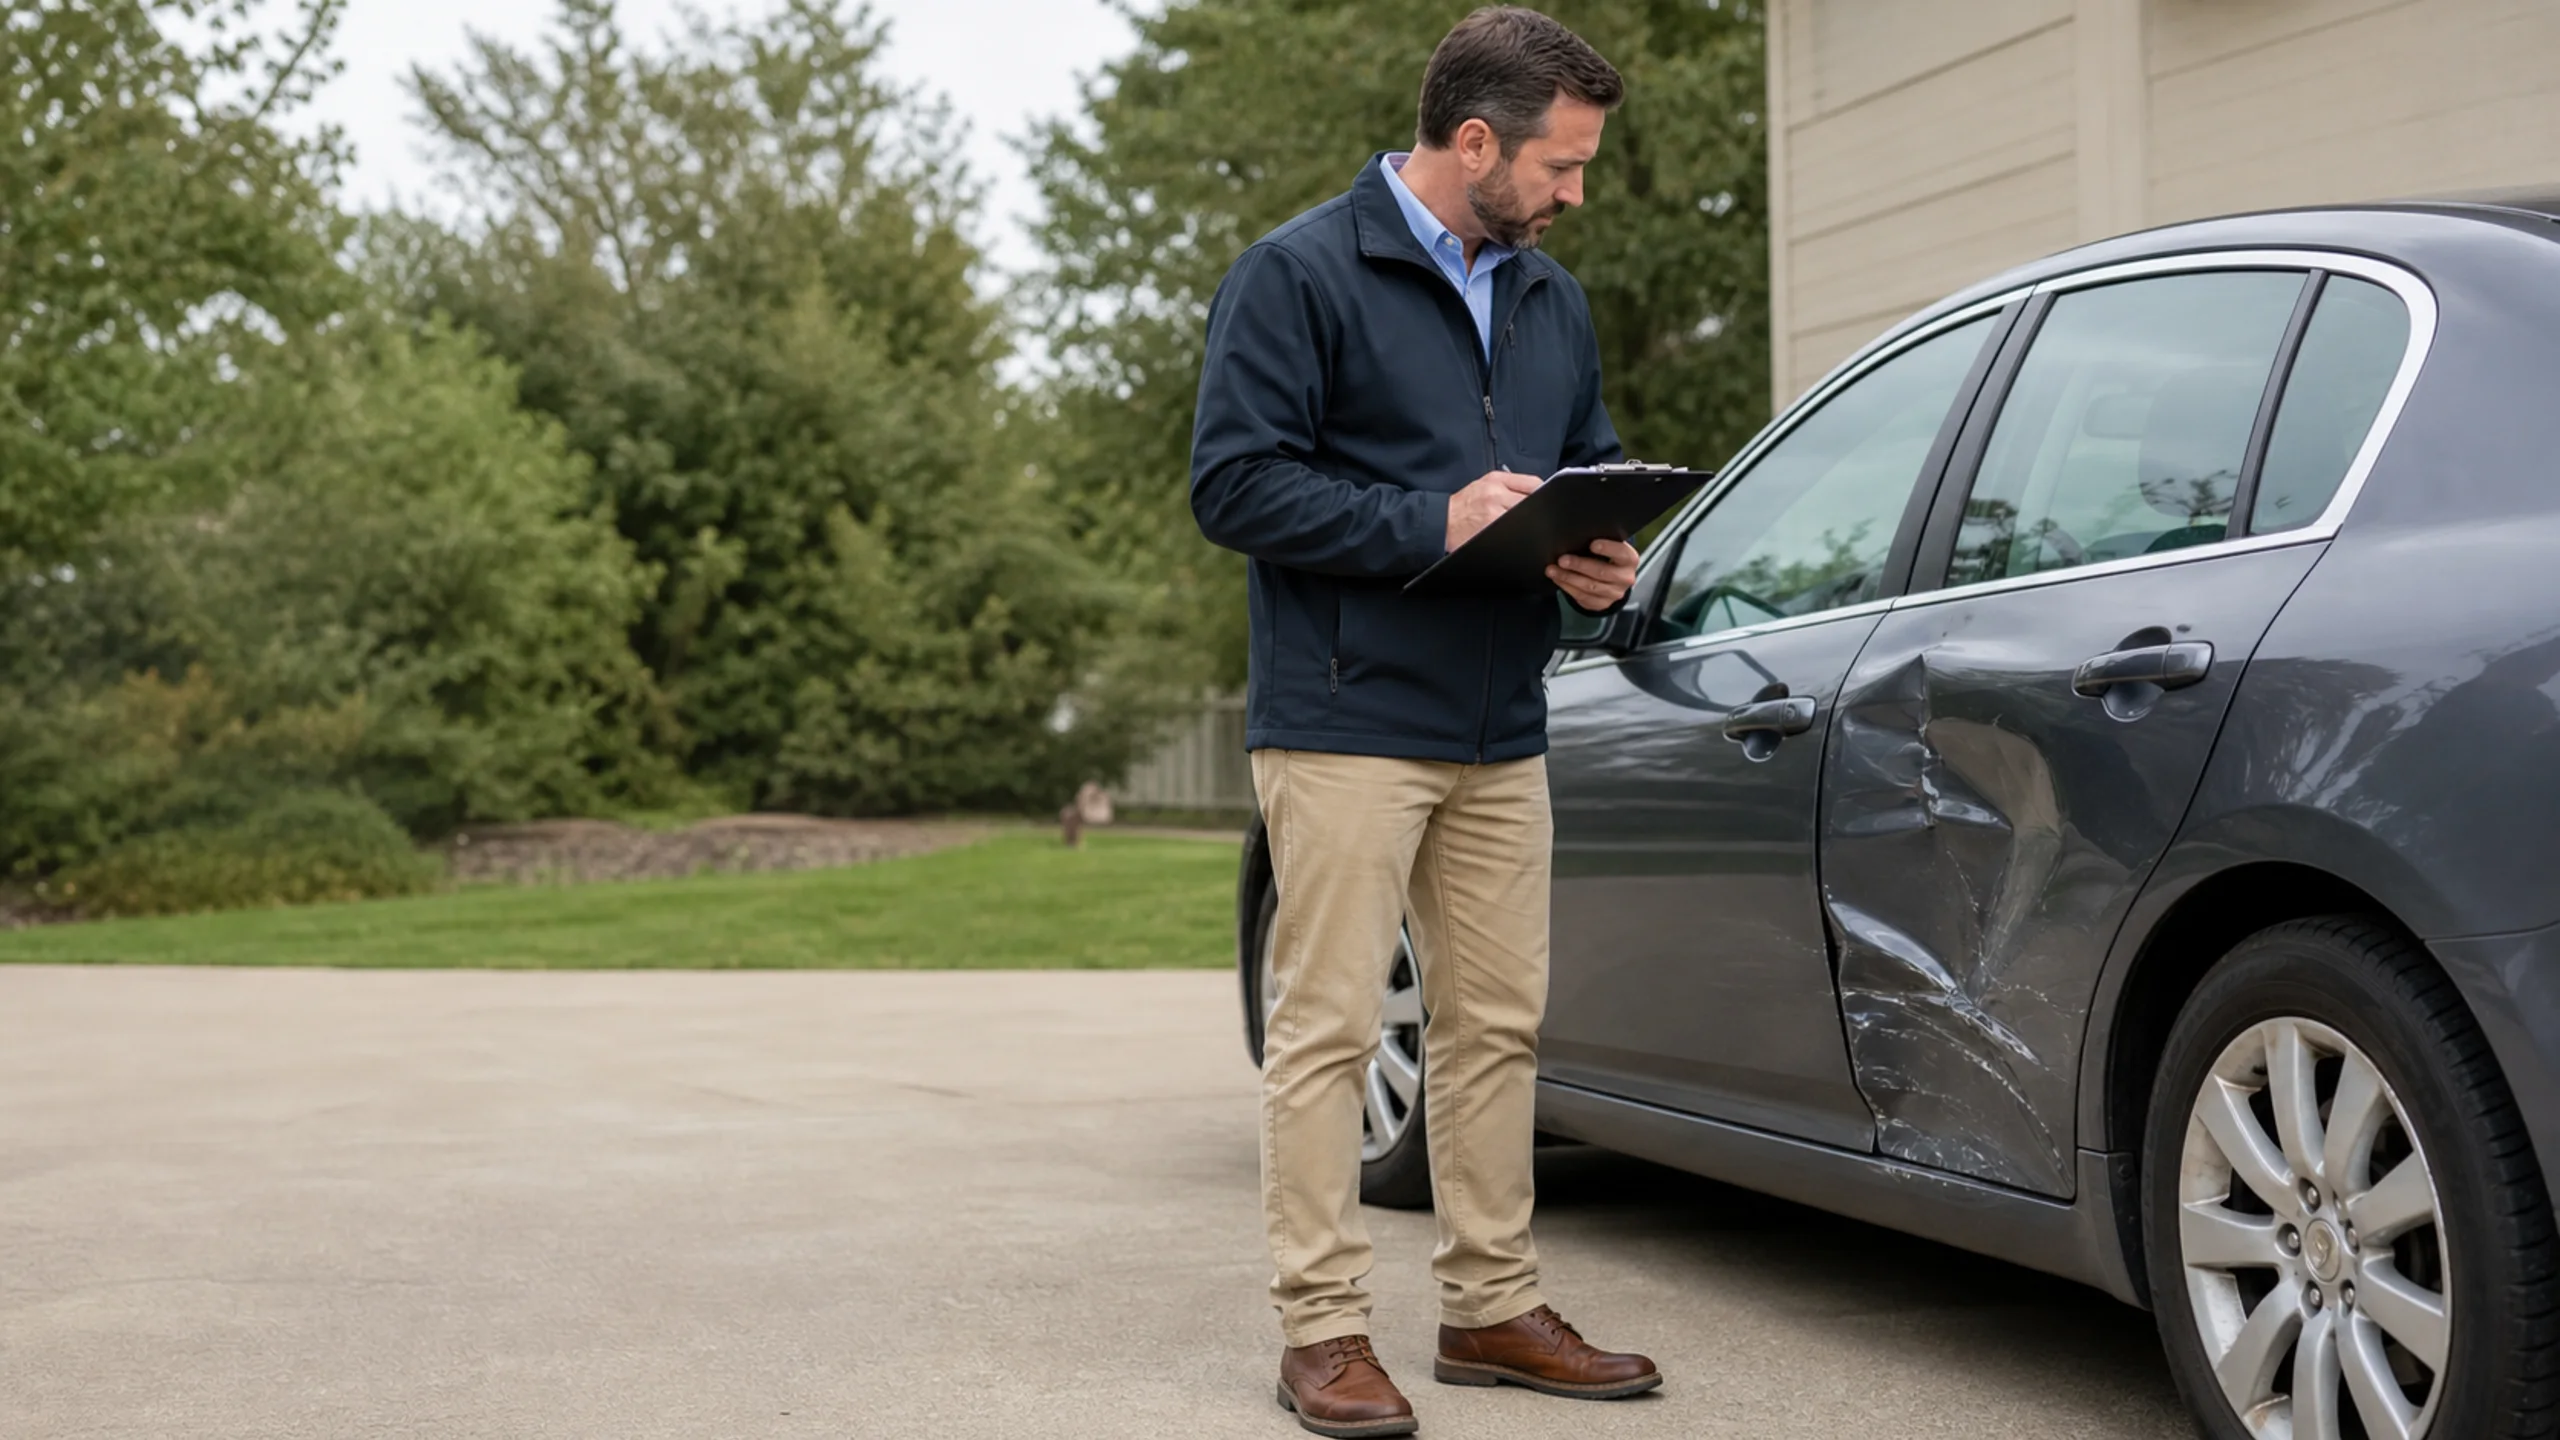
A repaired vehicle can still lose resale and trade-in value after a crash. Kentucky drivers may pursue that loss from the at-fault driver as part of a third-party property damage claim when the evidence shows the vehicle’s market value remains lower after repairs.
Diminished Value Defined
Diminished value is the difference between a vehicle’s market value before a crash and its market value after proper repairs. Repairs can restore function and appearance, but they do not remove an accident from a vehicle history report or erase a buyer’s concern about prior damage.
Vehicle history providers such as CARFAX and AutoCheck report many crashes and damage events. Those records can affect a dealer appraisal, a trade-in offer, or a private sale price. A clean-history vehicle and a repaired vehicle with the same year, trim, mileage, and condition do not always command the same price.
Kentucky diminished value claims usually involve one of two kinds of loss. Inherent diminished value is the market stigma that remains after competent repairs because the vehicle now has an accident history. Repair-related diminished value is added loss caused by incomplete or substandard repairs, such as panel misalignment, paint mismatch, structural issues, or improper replacement parts.
Kentucky Third-Party Claims
Kentucky property damage law can permit recovery for a repaired property’s remaining loss in market value from the party who caused the damage. In Muncie v. Wiesemann, a 2018 case involving contaminated real estate, the Kentucky Supreme Court recognized that stigma damages may be recovered along with repair costs when needed to reach the property’s full diminution in market value.
A third-party claim is a claim against the at-fault driver. In practice, the at-fault driver’s liability insurer usually evaluates and negotiates the claim, but the legal responsibility arises from the driver’s negligence and the resulting property damage.
A claim under the owner’s own collision policy is a separate question. First-party diminished value coverage depends on the policy language, including exclusions and limitations. The declarations page, endorsements, and loss-settlement provisions show what the policy says, and the owner can request the specific policy language an insurer relies on before accepting its answer.
Filing Deadline
Kentucky law generally allows two years to bring an action for injury to personal property. Under KRS 413.125, that action must be commenced within two years from the time the cause of action accrued. An appraisal, repair documentation, and insurer review all take time, so a diminished value demand belongs well before that deadline.
The date that controls a lawsuit can depend on the facts and the legal theory, and ongoing repair negotiations do not stop the limitations period.
Valuation Methods and Evidence
The central question is whether the vehicle’s market value after repairs is lower than its market value before the crash. Kentucky law does not impose one mandatory diminished value formula.
An insurer may use the “17c” formula, a method that originated in a Georgia diminished value settlement. It starts with a percentage of pre-loss value and reduces that figure for damage severity and mileage. It is an insurer valuation tool, not a Kentucky statutory formula or an automatic ceiling on a supported claim. The strongest claim rests on vehicle-specific market evidence.
Independent Appraisal
A qualified independent appraiser can inspect the repaired vehicle, review the repair file, examine the vehicle history, and compare the vehicle with clean-history market listings or sales. A useful report explains the appraiser’s method and gives the insurer documents it can evaluate.
Dealer Appraisals and Market Comparables
Written trade-in offers and clean-history comparables can also support the claimed loss. Dealer comparisons carry the most weight when the comparable vehicles share the same model year, trim, mileage range, drivetrain, condition, and equipment. An undocumented verbal estimate from a dealer carries far less weight than a written appraisal or a detailed market comparison.
Book-value tools from Kelley Blue Book, J.D. Power, and Edmunds can establish a starting point, but they do not replace vehicle-specific market evidence.
Factors That Affect Value Loss
The size of a diminished value claim depends on the vehicle and the damage. These facts usually drive the analysis:
- Damage severity, including structural repairs, airbag deployment, welding, suspension work, and multiple damaged panels.
- Vehicle age, mileage, trim level, condition, and pre-crash service history.
- Market demand for the make and model.
- Prior accidents or damage on the vehicle history report.
- Repair quality, repair documentation, and the parts used.
- Whether the title or history record carries a salvage, rebuilt, or similar brand.
Evidence to Gather
The claim file is easiest to build before the vehicle is traded, sold, or altered again. These records support the claim:
- The crash report, claim number, and the at-fault driver’s insurance information.
- Pre-crash photographs, maintenance records, the window sticker, and purchase documents.
- Repair estimates, final invoices, photographs, parts invoices, and calibration records.
- Vehicle history reports from CARFAX or AutoCheck.
- The vehicle identification number and original equipment details, which can be checked through the NHTSA VIN Decoder.
- The independent appraisal report, dealer trade-in appraisals, and clean-history market comparables.
- All emails, letters, valuation reports, and settlement communications from the insurer.
Written Demand to the Insurer
A written demand creates a clear record of the amount sought and the reasons for it. It goes to the liability insurer after the vehicle has been repaired and the documentation supports a specific loss amount.
The demand should include the crash date, claim number, vehicle identification, repair documents, valuation evidence, and the requested diminished value amount, along with a request for the insurer’s written valuation and the basis for any denial or reduced offer.
Kentucky’s Unfair Claims Settlement Practices Act, KRS 304.12-230, prohibits specific claim-handling conduct, including misrepresenting pertinent facts or policy provisions, refusing to pay without a reasonable investigation, and failing to promptly provide a reasonable explanation for a denial or compromise offer. Those rules do not make every valuation disagreement bad faith, but they set standards for claim conduct.
Common Insurer Responses
A carrier may contend that repairs returned the vehicle to pre-crash condition, that there is no loss until the owner sells the vehicle, or that its internal formula resolves the claim. Evidence supporting the claimed number answers those positions better than general statements about accident stigma.
When an insurer says diminished value is unavailable, the owner can request that position in writing, along with the authority or policy provision behind it. When the insurer offers a formula-based amount, its assumptions can be compared with the repair scope, vehicle history, mileage, and local market evidence.
A property damage release that resolves diminished value ends that claim. Signing one makes sense only when the payment includes that loss or the owner intends to release it.
Special Coverage Situations
A diminished value claim changes when the vehicle is totaled, the at-fault driver is uninsured, or an injury claim sits alongside the property damage file.
Total-Loss Claims
Diminished value generally applies to a vehicle that is repaired and returned to service. When a vehicle is declared a total loss, the dispute usually centers on actual cash value, condition adjustments, taxes, title fees, and the comparable vehicles the insurer used. The trim, options, mileage, and condition in the insurer’s valuation should all be checked for accuracy. Kentucky property damage claims and totaled car claims in Kentucky cover those options in more detail.
Uninsured At-Fault Drivers
When the at-fault driver has no liability insurance, recovering a diminished value loss becomes more complicated. Uninsured and underinsured motorist coverage often focuses on bodily injury, while property damage coverage depends on the policy and its endorsements. The policy’s uninsured motorist property damage provisions, collision coverage, deductibles, and diminished value language decide what is available.
Injury Claims Alongside Property Damage
Legal representation can be useful when the property damage claim overlaps with an injury case, repairs reveal structural damage, the carrier disputes liability, or a release arrives before the full claim has been evaluated. An attorney can assess the available claim paths, evidence, deadlines, and release language. Sam Aguiar Injury Lawyers offers a free case review for Kentucky car accident claims that involve injuries as well as vehicle damage.
Ready to Take Action on Your Injury Claim?
After a serious injury, medical bills pile up while the insurance company looks for ways to pay you less. Most law firms take their cut first and leave you with whatever is left. Sam Aguiar Injury Lawyers does things differently. With our exclusive Bigger Share Guarantee®, you always get more. Every client gets a dedicated three-person team: an attorney, a case manager, and a legal assistant. We never raise our fee rate if we have to go to court, and you pay $0 Out-Of-Pocket Forever.
Frequently Asked Questions
1Can I claim diminished value in Kentucky?+
2Does a perfect repair eliminate diminished value?+
3Is the 17c formula required in Kentucky?+
4How long is there to file a diminished value claim in Kentucky?+
5Does the vehicle have to be sold before claiming diminished value?+
6Can diminished value be recovered if the car was totaled?+
Latest Articles

FMCSA Revoked ELDs: Fleet Compliance and Enforcement Deadlines
FMCSA removed five electronic logging devices from the registered list on August 6, 2026, and set an October.

FMCSA English Proficiency Rule and OOS Enforcement
FMCSA English Proficiency Rule Sam Aguiar Injury Lawyers August 11, 2026 7 minute read On This Page.
New Jersey Amazon DSP Antitrust Lawsuit
New Jersey Amazon DSP Antitrust Lawsuit Sam Aguiar Injury Lawyers August 11, 2026 7 minute read On This Page.